The Rebalance Moves More Money Than the News Does
An addition to a major index obliges a large and predictable set of buyers to act on a known date. That predictability is the whole opportunity, and the whole problem.
Saturday, September 26, 2026
An addition to a major index obliges a large and predictable set of buyers to act on a known date. That predictability is the whole opportunity, and the whole problem.
Shareholder meetings were a scheduling exercise for decades. Rising opposition on pay, board composition and auditor tenure has made the outcome uncertain enough to require actual campaigning.
Corporate bond ETFs now supply much of the liquidity that dealer balance sheets used to. The mechanism works well and has been tested mainly in conditions that were not the hard case.
Vehicles offering private-market exposure with periodic liquidity have gathered enormous sums from investors who have never needed to leave. The gate is the product, and most holders have not read it.
Private funds promised distributions on a timetable that stopped being met. The secondary market has grown from a distressed corner into the mechanism by which investors get money back at all.
A large stock of corporate debt issued at generational lows is coming due into a market priced very differently. The refinancing is available; what has changed is what it costs and who it is available to.
Sell-side coverage of companies below a billion dollars has thinned to almost nothing. The consequence is not merely obscurity — it is a measurable discount that persists regardless of what the business does.
Lending out the shares a fund holds has offset fees for years and rarely appears in the conversation about cost. As balances grow, the question of who keeps the proceeds is getting harder to leave unasked.
Fund launches have been outpaced by closures for the first sustained stretch in the product's history. The survivors reveal what the proliferation was actually for.
The asset class that ate corporate lending is maturing. What it built while growing is now permanent market structure.
Share repurchases are running at a substantial pace again, and the companies doing them have learned to explain themselves. Disclosure has improved faster than the underlying discipline.
The sleepiest corner of American finance is being dragged into the present by electronic trading, better disclosure and a generation of buyers who expect both.
Broad market index funds have become substantially less diversified than the word index implies. Institutional allocators are reworking mandates written when the assumption held.
Futures markets have spent the summer walking back easing expectations, and portfolio managers are adjusting duration, credit and cash accordingly.
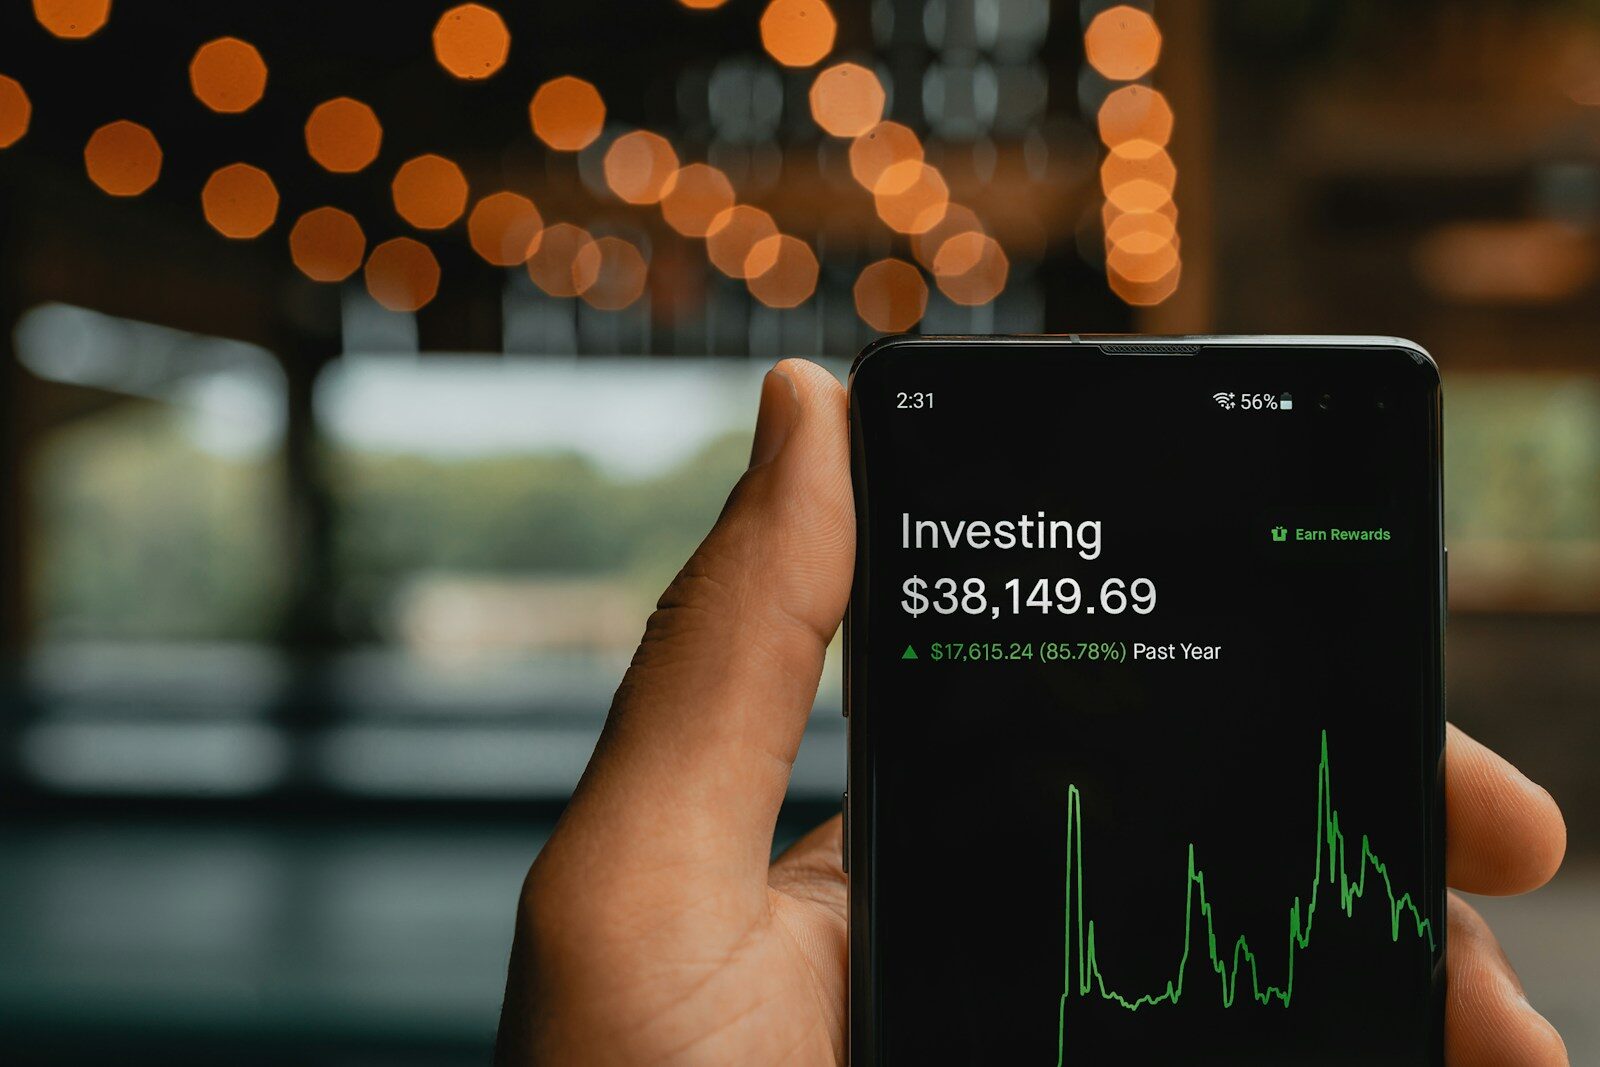
The meme-stock cohort did not disappear when the fever broke. It aged into the most financially engaged retail generation in decades, with the account balances to show it.
After a long drought, public listings are returning in cautious single file. The companies going first are teaching everyone else the new rules.
After a decade in which payouts read as an admission of exhausted ambition, companies and investors have rediscovered the discipline of cash returned.