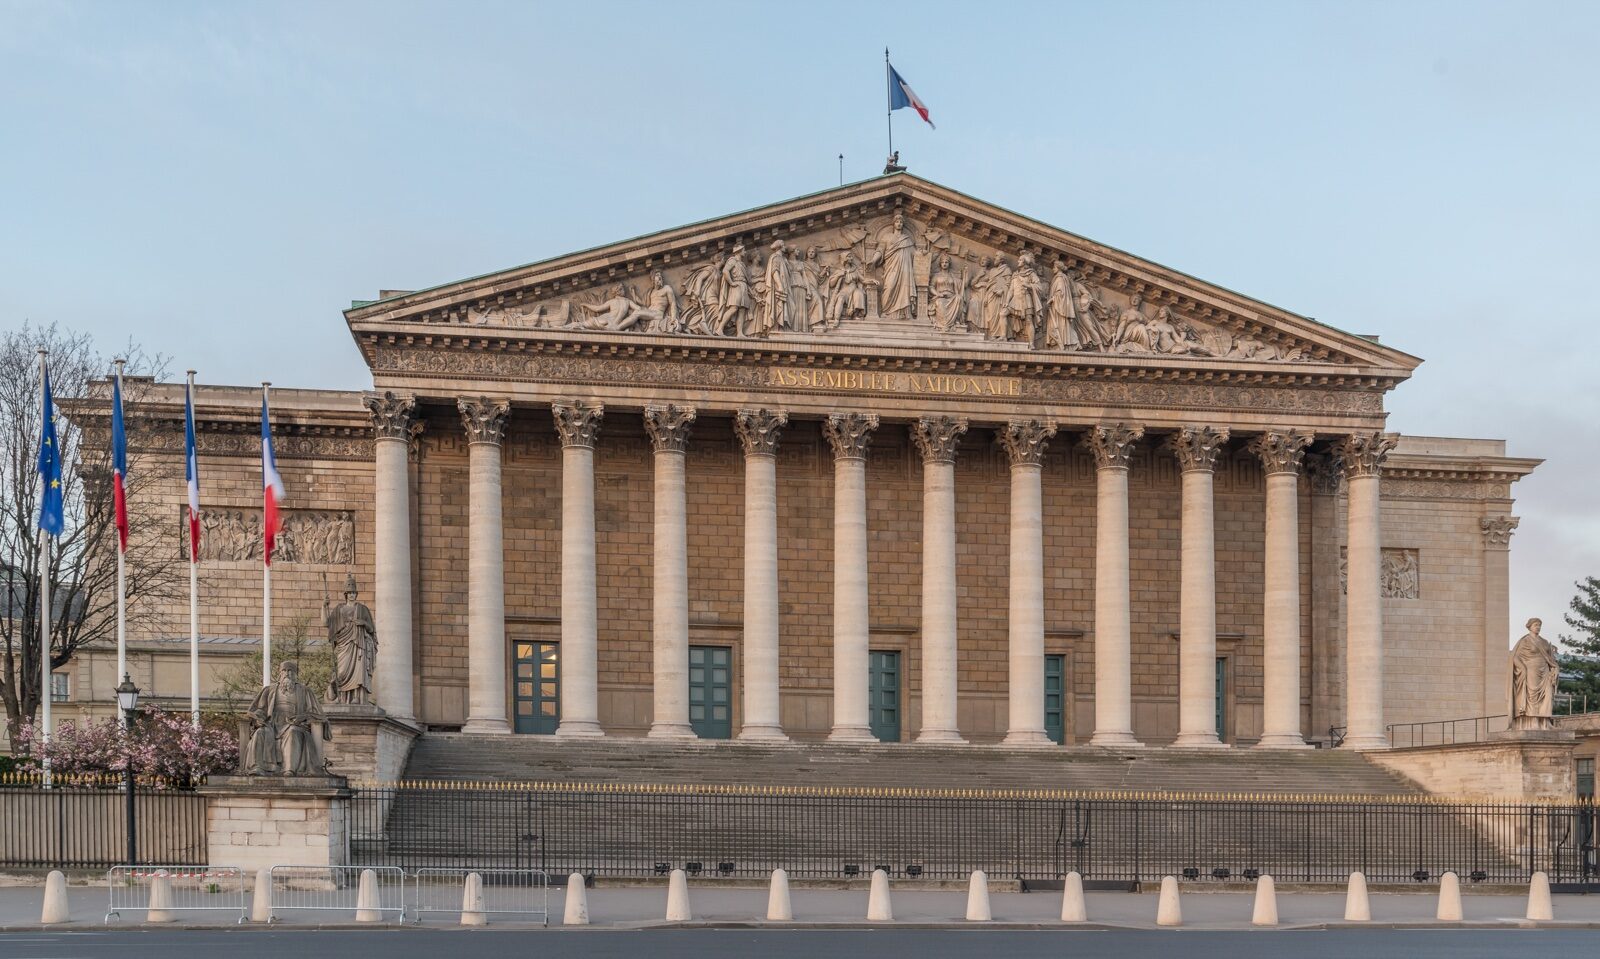
France's National Assembly holds its first major vote on the revenue side of the 2027 budget on Tuesday 20 October, and the committee that examined it first has already said no. The Assembly's finance committee rejected the revenue package by 31 votes to 3, with two abstentions, according to TradeTheNews.com commentary published by FXStreet. A committee rejection does not bind the chamber, which debates the government's text, but in a parliament with no stable majority it is the closest reading of how members lean.
The bond market has been pricing the difficulty for weeks. France's 10-year government bond closed at about 4.79 per cent on Friday 16 October, against 3.41 per cent for the German Bund, according to Trading Economics. That puts the gap at about 137 basis points by this publication's arithmetic, below its peak but far above where it stood in late summer.
What the budget asks for
The government proposes a €54 billion fiscal adjustment, about €43 billion of it new measures and €11 billion from earlier decisions, FXStreet reports. ING says the deficit would otherwise reach about 6.5 per cent of GDP in 2027. The plan aims for 5.0 per cent, down from an expected 5.4 per cent this year and 5.1 per cent in 2025.
ING lists the main measures. On revenue: a lower tax allowance for pensioners, new taxation of sick-leave and termination payments, fewer exemptions and anti-fraud steps. On spending: a freeze on ministerial budgets, civil service pay, housing benefits and family allowances, and no inflation indexation for higher pensions, worth €4.1 billion. Interest payments rise by €12 billion to €91 billion, which by this publication's arithmetic puts this year's bill near €79 billion. Public debt, about 119 per cent of GDP in mid-2026, would still rise to 121.7 per cent next year. ING says a 5 per cent deficit slows the deterioration but does not stabilise debt.
How far the market has moved
Allianz Trade's economists wrote on 9 October that France is "the hardest hit in the global bond sell-off, mostly due to its own fiscal and political weakness." Since the Hormuz crisis began, they say, 10-year French yields have risen 150 basis points, against 115 for U.S. Treasuries, 132 for Italy and 83 for Germany, and the spread over Bunds peaked at 150 basis points. ING puts the spread at 86 basis points at the start of September. Allianz describes the speed of the move as "a positioning shock, not a pure repricing of fundamentals," with market depth more than 50 per cent below normal.
The shock is global in origin. As we reported, the IMF's July forecast assumed $89 oil this year, and crude has traded far above that since. But Allianz argues France is exposed by its own record: a deficit above 5 per cent of GDP for four years running, and debt up from 98 per cent of GDP in 2019.
Why the ECB is not the answer yet
ING says the European Central Bank's Transmission Protection Instrument, its tool against disorderly spread widening, is unlikely to be used early, because it generally requires the French budget to be fully adopted in line with EU fiscal rules. It quotes Banque de France governor Emmanuel Moulin: "these mechanisms are only used if measures are taken at a national level." Allianz expects the ECB to limit itself to words for now, and says it would take a severe scenario, with spreads of 175 to 200 basis points, to change its approach.
That is why Tuesday is a step, not a verdict. ING's base case is that a modified budget is adopted under Article 49.3 of the constitution, which lets a government pass a text without a vote unless an absolute majority backs a motion of no confidence. Allianz also expects a budget by year-end, by ordinance or by 49.3. Parliament has 70 days for the state budget and 50 for social security, ING notes, so the real deadlines fall between late November and mid-December. Allianz lists Assembly votes on 20 and 27 October.
What to watch
The first test is Tuesday's result, and whether the government answers a defeat with concessions or with a procedural route around the chamber. The second is the spread: ING expects it to stay well above 100 basis points and more likely to test about 150. The third is the 2027 presidential election, set for 18 April and 2 May, around which Allianz builds its four scenarios. A vote can change the budget. Only a budget can change the spread.
Sources
- TradeTheNews.com via FXStreet, "French risk spreads from OATs into the Euro as Assembly takes up the Budget," 13 October 2026: https://www.fxstreet.com/analysis/french-risk-spreads-from-oats-into-the-euro-as-assembly-takes-up-the-budget-202610130958
- Trading Economics, France 10-year government bond yield, close of 16 October 2026: https://tradingeconomics.com/france/government-bond-yield
- ING Think, "France's budget offers no quick relief for bond markets," 1 October 2026: https://think.ing.com/articles/frances-budget-offers-no-quick-relief-for-bond-markets/
- Allianz Trade, "Toasted, not burnt: France's bond sell-off and the road to the 2027 election," updated 9 October 2026: https://www.allianz-trade.com/en_global/news-insights/economic-insights/Toasted-not-burnt-France-bond-and-the-road-2027-election.html
The committee vote, the 20 October date, the €54 billion adjustment, its €43 billion and €11 billion parts and the debt projection come from TradeTheNews.com market commentary published by FXStreet on 13 October 2026. The 16 October closing yields for France and Germany come from Trading Economics; the 137 basis point gap is this publication's arithmetic from them. The deficit path, the measures, the €12 billion rise in interest payments to €91 billion, the move in the spread from 86 basis points to above 130, the Article 49.3 base case, the TPI comments and the Banque de France quote come from ING Think, by Charlotte de Montpellier, Benjamin Schroeder, Peter Vanden Houte and Carsten Brzeski, dated 1 October 2026. The 150 basis point peak, the yield moves since the Hormuz crisis, the market-depth figure, the 20 and 27 October votes, the scenarios and the quoted phrases come from Allianz Trade Economic Insights, updated 9 October 2026. The 2026 interest bill is this publication's arithmetic. The analysis is our own.