Micron Technology reported a quarter on 30 September that would have been hard to imagine three years ago. Revenue for the fiscal fourth quarter, which ended on 3 September, was $54.23 billion, up 379 percent from $11.32 billion a year earlier. Non-GAAP gross margin was 87 percent. GAAP net income was $37.70 billion, against $3.20 billion a year earlier. For the full fiscal year, revenue reached $133.19 billion, up 256 percent, with $84.97 billion in net income, according to Micron's results announcement.
The stock went sideways.
Shares closed at $1,065.11 on the day of the report and rose slightly in extended trading, CNBC reported. The next morning they were down 3 percent at $1,034.34, then recovered to close up about 3 percent at $1,097.39. By the close on Tuesday, 6 October, they were at $1,045.56, about 2 percent below where they stood before the results. For a company whose shares CNBC said had risen more than 500 percent over the past year, a week of round trips is close to standing still.
That disconnect is the story. The fourth quarter was Micron's sixth consecutive quarterly revenue record, the company said on its earnings call. It took in more revenue in 13 weeks than in all of fiscal 2025, when full-year sales were $37.38 billion. Sequentially, revenue climbed 31 percent from $41.46 billion in the prior quarter. DRAM brought in $39.8 billion, about 73 percent of the total, while NAND contributed $14.1 billion.
Pricing Did Much of the Work
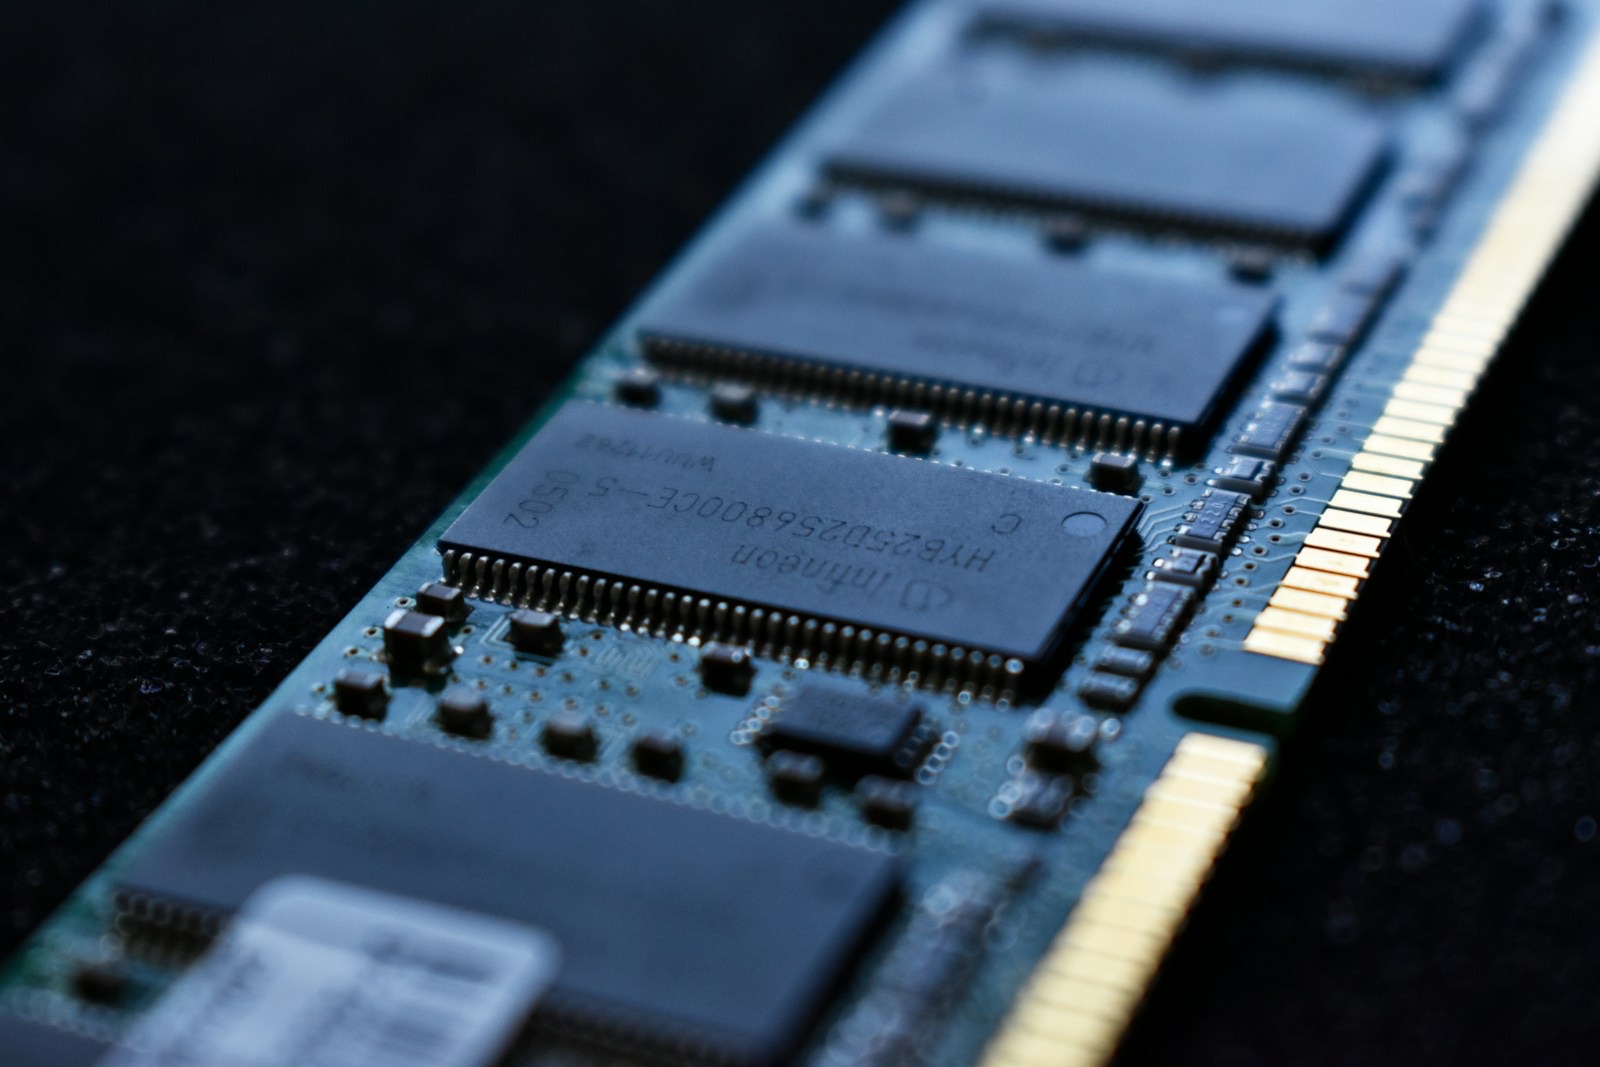
The mechanics of the quarter matter more than the headline. On the call, Micron said DRAM bit shipments rose by a mid-single-digit percentage from the prior quarter while DRAM prices rose by a high-teens percentage. In NAND, bit shipments rose about 10 percent and prices about 30 percent. Non-GAAP gross margin rose from 45.7 percent a year earlier to 87.0 percent, which means most of the extra revenue from higher prices flowed through to profit rather than being absorbed by higher production costs.
Much of that pricing power comes from AI data centers and from high-bandwidth memory, or HBM, the stacked DRAM that sits alongside AI accelerators. CNBC described SK Hynix and Samsung as the HBM leaders, with Micron holding the smallest share of the three. Micron said on the call that it has completed agreements covering the vast majority of its calendar 2027 HBM supply, with significant year-on-year price increases.
The data center numbers show where the money is coming from. Revenue in Micron's Core Data Center Business Unit was $18.00 billion in the quarter, against $1.58 billion a year earlier, and its Cloud Memory Business Unit brought in $16.28 billion, against $4.54 billion. "Micron delivered record fiscal 2026 results, and we expect an even stronger fiscal 2027," chief executive Sanjay Mehrotra said in the announcement, adding that the company's strategic customer agreements "provide added confidence in the durability of Micron's financial performance."
That contracted visibility is both the bull case and the bear case. When so much of the growth story rests on price rather than volume, the market starts asking what happens when supply catches up. CNBC noted that SK Hynix and Samsung are building large new HBM factories in South Korea, and Micron itself is investing in new fabs in Idaho and New York. Each new line of capacity is, in time, a threat to the scarcity that sets today's prices.
There is also the customer side to consider. Every dollar of memory margin Micron captures is a dollar of cost for the companies building AI data centers. In our view, the pricing power that is real today is also the incentive for customers to look for ways to need less of it tomorrow.
The Bar Keeps Moving
Micron guided first-quarter fiscal 2027 revenue to $61.5 billion, plus or minus $1.5 billion, at a non-GAAP gross margin of about 86.25 percent. Analysts polled by LSEG had expected $57 billion, CNBC reported. Guidance that would have seemed absurd a year ago now reads as merely meeting the bar. That is the trap of six consecutive records: each print resets expectations, and the bar is now at a height where only perfection clears it.
Memory has long been a cyclical business, and the current cycle has been stretched by AI demand into an unfamiliar shape. Micron told investors it expects supply to remain tight through 2028. If that proves wrong, the fall will be measured from a much greater height.
The quarterly and annual revenue, net income, gross margin, business unit revenue, guidance and the remarks of Sanjay Mehrotra in quotation marks are from Micron's results announcement of 30 September 2026, distributed on GlobeNewswire. The DRAM and NAND revenue, bit shipment and pricing changes, the sixth consecutive quarterly revenue record and the statement on calendar 2027 HBM supply agreements are from Micron's earnings call of the same day, as summarised by Yahoo Finance. The analyst consensus, the year-on-year rise in DRAM revenue and the description of HBM market share are as reported by CNBC on 30 September 2026. The intraday share price on 1 October is as reported by 24/7 Wall St.; closing prices are Nasdaq closes as published by Yahoo Finance. Percentage changes in the share price, the year-on-year multiples for business unit revenue and the rounding of growth rates are this publication's arithmetic. The analysis is our own.
Topics technologysemiconductorsmemoryai