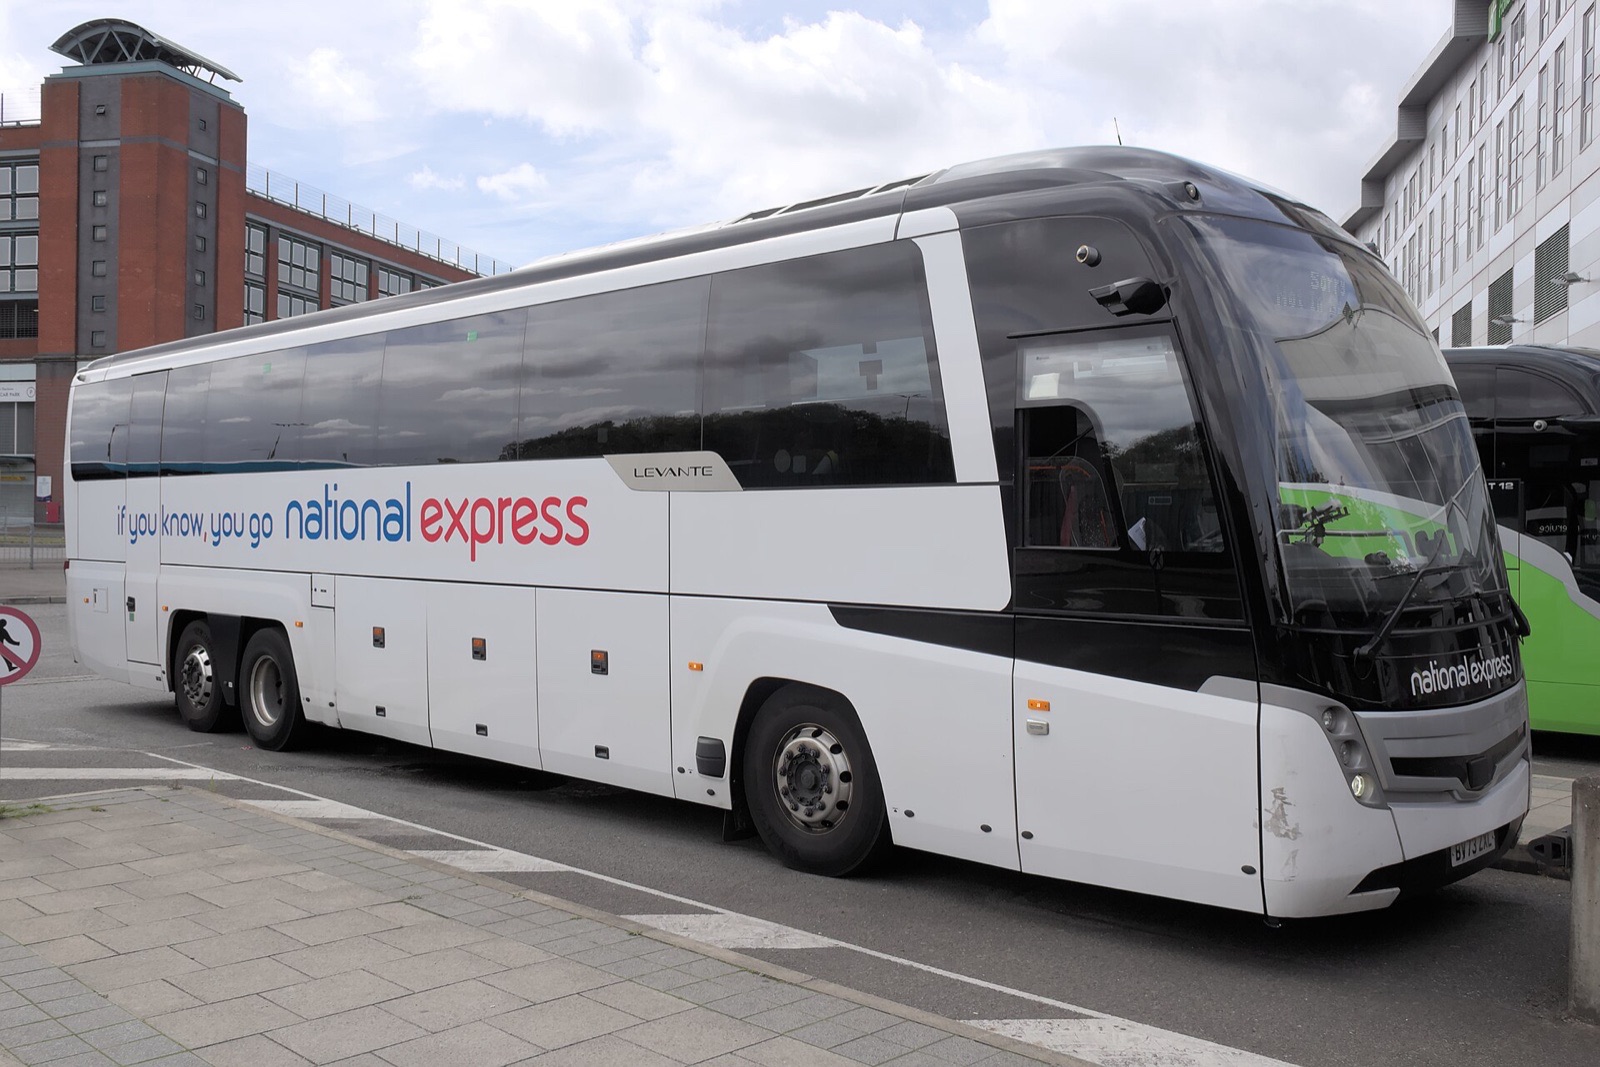
Mobico, the British company that owns National Express coaches and ALSA, which it describes as the market leader in Spanish road passenger transport, has agreed to be taken private for 46 pence a share in cash, valuing its equity at about £308 million, the two sides said on Friday 30 October.
The buyer is not a stranger. Leita Mobility is owned through Autobuses de León by the Cosmen family's CMC Group, which has been Mobico's largest shareholder since 2005, and by a fund run by Asterion Industrial Partners of Madrid. The price looks generous. The balance sheet explains why it is small.
What are shareholders being offered?
Cash, at a large premium to where the shares had been. The 46p price is 55.1 per cent above the 29.7p close on 20 October, the day before the offer period began, and 93.3 per cent above the 23.8p close on 3 August, according to the Rule 2.7 announcement. The first approach, on 4 August, was 38p. Mobico's shares rose about 11 per cent on Friday, Investing.com reported.
Autobuses de León is owned 50.1 per cent by the CMC Group and 49.9 per cent by Asterion Industrial Infra Fund III, which closed in 2025 with €3.4 billion of commitments. Before this deal it ran urban bus concessions in Malta and Cyprus with about €187 million of revenue last year.
Where does the £2.3 billion go?
Mostly to lenders. The announcement values Mobico at an enterprise value of about £2,323 million, 11.7 times its adjusted operating profit (EBIT) of £198 million for 2025. Its own bridge from enterprise value to equity shows what sits ahead of the shareholders.
| Claim on Mobico | Amount |
|---|---|
| Adjusted net financial debt, 31 March 2026 | £1,134 million |
| Hybrid notes | £500 million |
| Provisions | £285 million |
| Other adjustments, incl. pensions and minority interests | £97 million |
| Equity (46p a share) | About £308 million |
| Enterprise value | About £2,323 million |
Source: Rule 2.7 announcement, 30 October 2026. Rows do not sum exactly because of rounding in the announcement.
By this publication's arithmetic, the shares are about 13 per cent of the enterprise value. The hybrid alone is worth about 1.6 times all of the equity, and the bidder already holds about 53.6 per cent of it, or roughly £268 million at face value. The CMC Group's stake of about 26 per cent means the cash due to other shareholders is closer to £228 million, also by our arithmetic.
That arithmetic matters for the premium. When equity is a thin slice on top of a large debt stack, small changes in the business's value move the share price a lot. Mobico's independent directors said as much, warning that "modest changes in trading, foreign exchange, discount rates or legacy liabilities translate into disproportionately large impacts on the equity value." The same leverage that makes 46p a 55 per cent premium also made the shares cheap. The buyers of Wendy's this week face a milder version of the same arithmetic.
Why did the board agree?
Because of the debt calendar. Mobico's covenant gearing rose to 2.9 times at 31 March 2026, above its 1.5 to 2.0 target range, and about £230 million of U.S. private placement notes fall due in May and June 2027, the announcement says. Moody's rates the company B2 and Fitch rates it BB with a negative outlook. The directors concluded that staying independent would require "a holistic refinancing" before those notes mature, along with further disposals and restructuring.
"Despite the recent strategic progress, the financial position of the business remains challenging," Phil White, Mobico's non-executive chair, said in the announcement. The company reported a loss of £89.2 million for the 15 months to March, Investing.com said.
The bidder says it will refinance Mobico's senior debt after completion with a long-term "infrastructure-style" package and has commitments from Santander, CaixaBank and MUFG. It also says employees' pension rights will be safeguarded and employer contributions maintained. The cash price is funded from Autobuses de León's own cash and an interim facility.
Who decides?
The other shareholders. Because the Cosmen family is on the buying side, its shares, about 26.2 per cent of the total, will be bound by the scheme but cannot vote at the court meeting. Jorge Cosmen Menéndez-Castañedo, a Mobico director and family member, took no part in the board's decision. Approval needs a majority in number of the voting shareholders, holding 75 per cent of the value of shares voted. Only about 0.3 per cent of the voting shares are committed so far.
What to watch
The scheme document, which will set out the timetable and more detail on financing, is the next step, and completion is expected in the first half of 2027. The test is whether outside holders, who saw the shares at 23.8p in August, treat 46p as a rescue price or hold out for more. The Cosmen family's position on both the debt and the equity gives it a strong hand. It does not give it the vote.
The offer terms, premiums, enterprise value and valuation bridge, ownership of the bidder, the 38p first proposal, the irrevocable undertakings, the debt figures, credit ratings, US private placement maturities, the reasons given by Mobico's independent directors, the financing commitments, the pension intentions, and the quotations from Phil White and the independent directors are from the Rule 2.7 announcement published by Leita Mobility and Mobico on 30 October 2026. The 11 per cent share price rise and Mobico's £89.2 million loss are as reported by Investing.com on 30 October 2026. The equity share of enterprise value, the comparison with the hybrid, the value of the bidder's hybrid holding and the cost of buying out other shareholders are this publication's arithmetic. The analysis is our own.
Topics businessprivate equitydebt