The Beneficiary Form Beats the Will, and Almost Nobody Checks It
Retirement accounts and life insurance pass by beneficiary designation, not by will. The designation is usually older than the marriage, and nobody is reminded to look at it.
Friday, October 16, 2026
Retirement accounts and life insurance pass by beneficiary designation, not by will. The designation is usually older than the marriage, and nobody is reminded to look at it.
Overdraft charges have fallen sharply, which is a real gain for the households that paid them. The cost of a checking account did not fall, because it moved somewhere less visible.
Going without homeowners coverage was a fringe decision made by people with no choice. It is becoming a calculated one, made by owners who ran the numbers and did not like them.
Unpaid medical bills were pulled from consumer credit reports because they predicted repayment poorly. Households gained real ground. Lenders went looking for the information somewhere else.
Assessment cycles lag transactions by years, which means households are receiving bills based on a market that has already turned. The lag is the problem, not the rate.
Car payments have climbed faster than incomes for most of a decade, and the loans stretched to absorb the difference. Delinquency is now rising in a category households historically protected above almost everything else.
Title, escrow, recording and settlement fees are disclosed on every mortgage and compared by almost no one. The line has grown faster than the loan it attaches to, and buyers pay it once and forget it.
Private equity, private credit and real assets are arriving inside ordinary retirement plans, bringing diversification arguments and fee questions in equal measure.
Higher rates taught small companies that idle cash has a price. The habits they built are outlasting the rates that created them.
The best-taxed account in the American system was designed for medical bills and is increasingly being used as a supplemental retirement fund by the people who least need help saving.
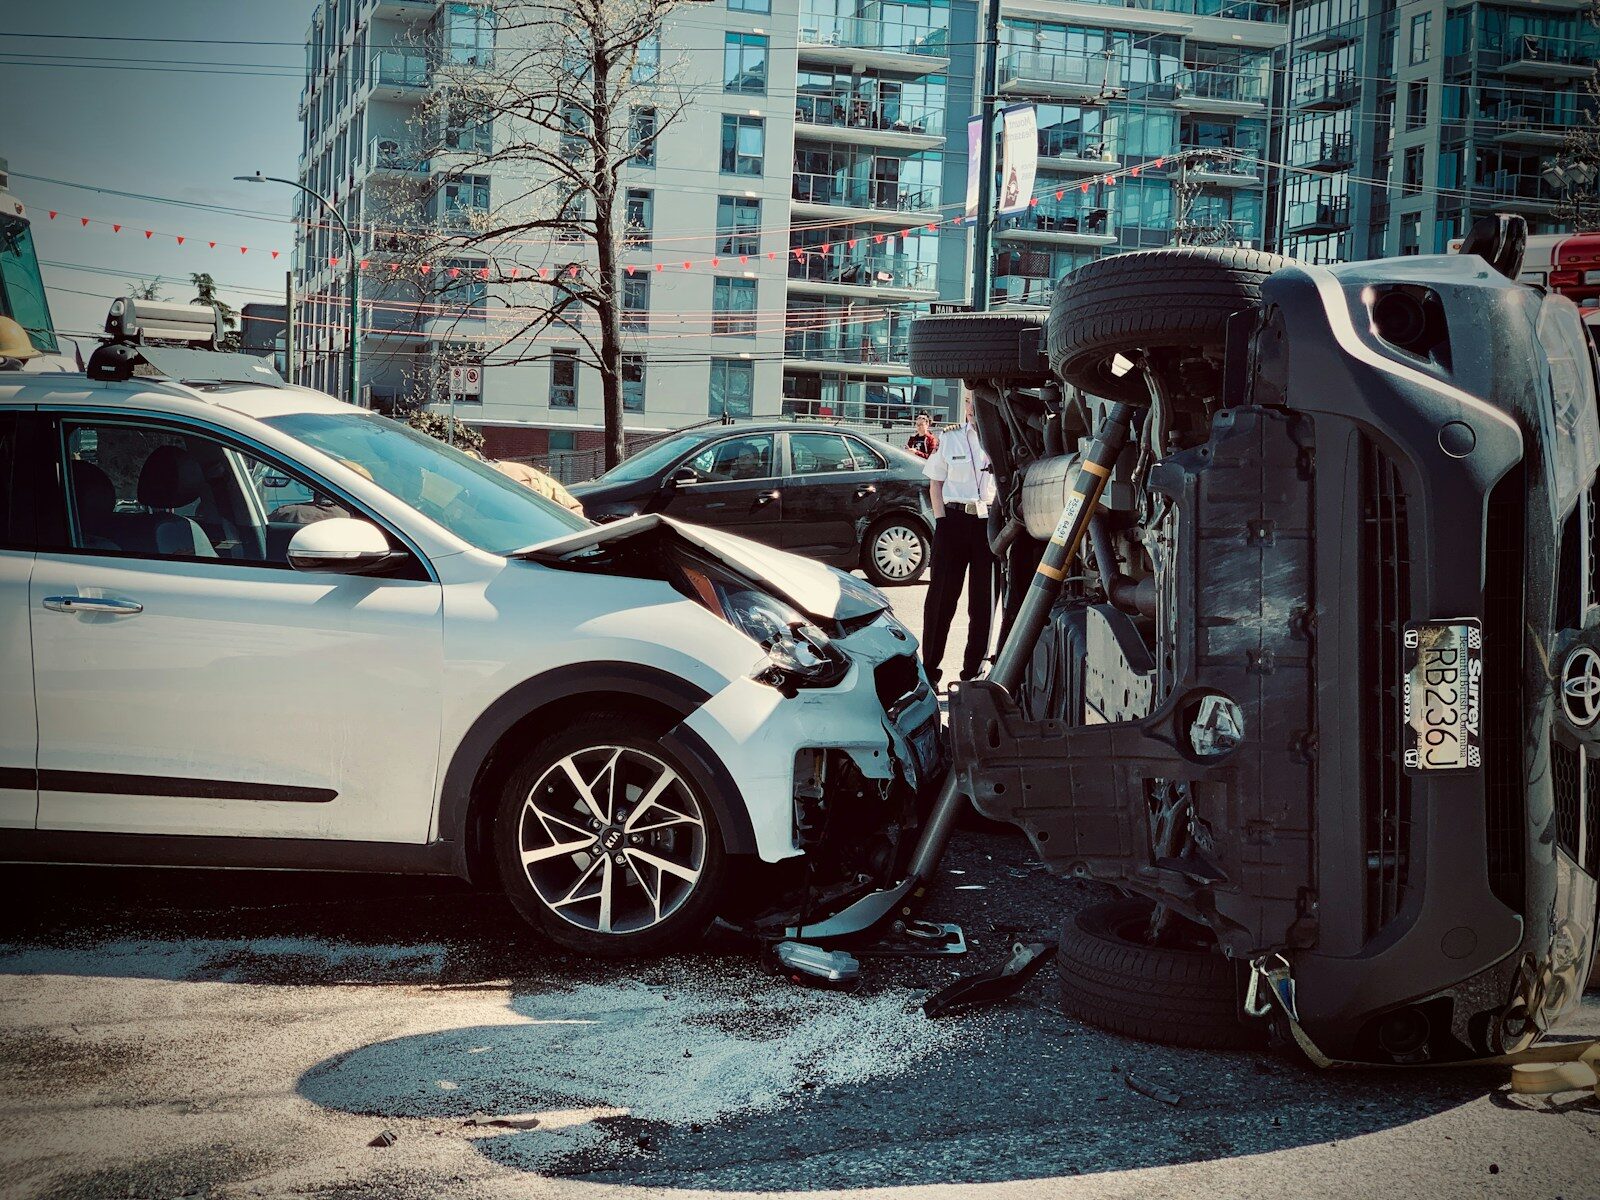
Headline inflation cooled, but households keep feeling squeezed, and the culprit hiding in the budget is insurance: home, auto and health premiums repricing years of accumulated risk.
Installment lending at the checkout spent years invisible to the credit system. As it becomes reportable, both the lenders and the borrowers are discovering what visibility costs.
After years of earning nothing, household savers have become rate shoppers, and the deposit market is behaving like a market again.
Facing depositors who can move money in seconds, smaller banks are investing in retention tooling that watches balances the way retailers watch shopping carts.
The largest generational wealth transfer on record is underway. Most of it is moving to households that were already comfortable, and much of it is being consumed by end-of-life costs before it moves at all.
Beneath the affordability complaints, savings behavior has shifted. Households are extinguishing revolving debt at rates not seen in a decade.